
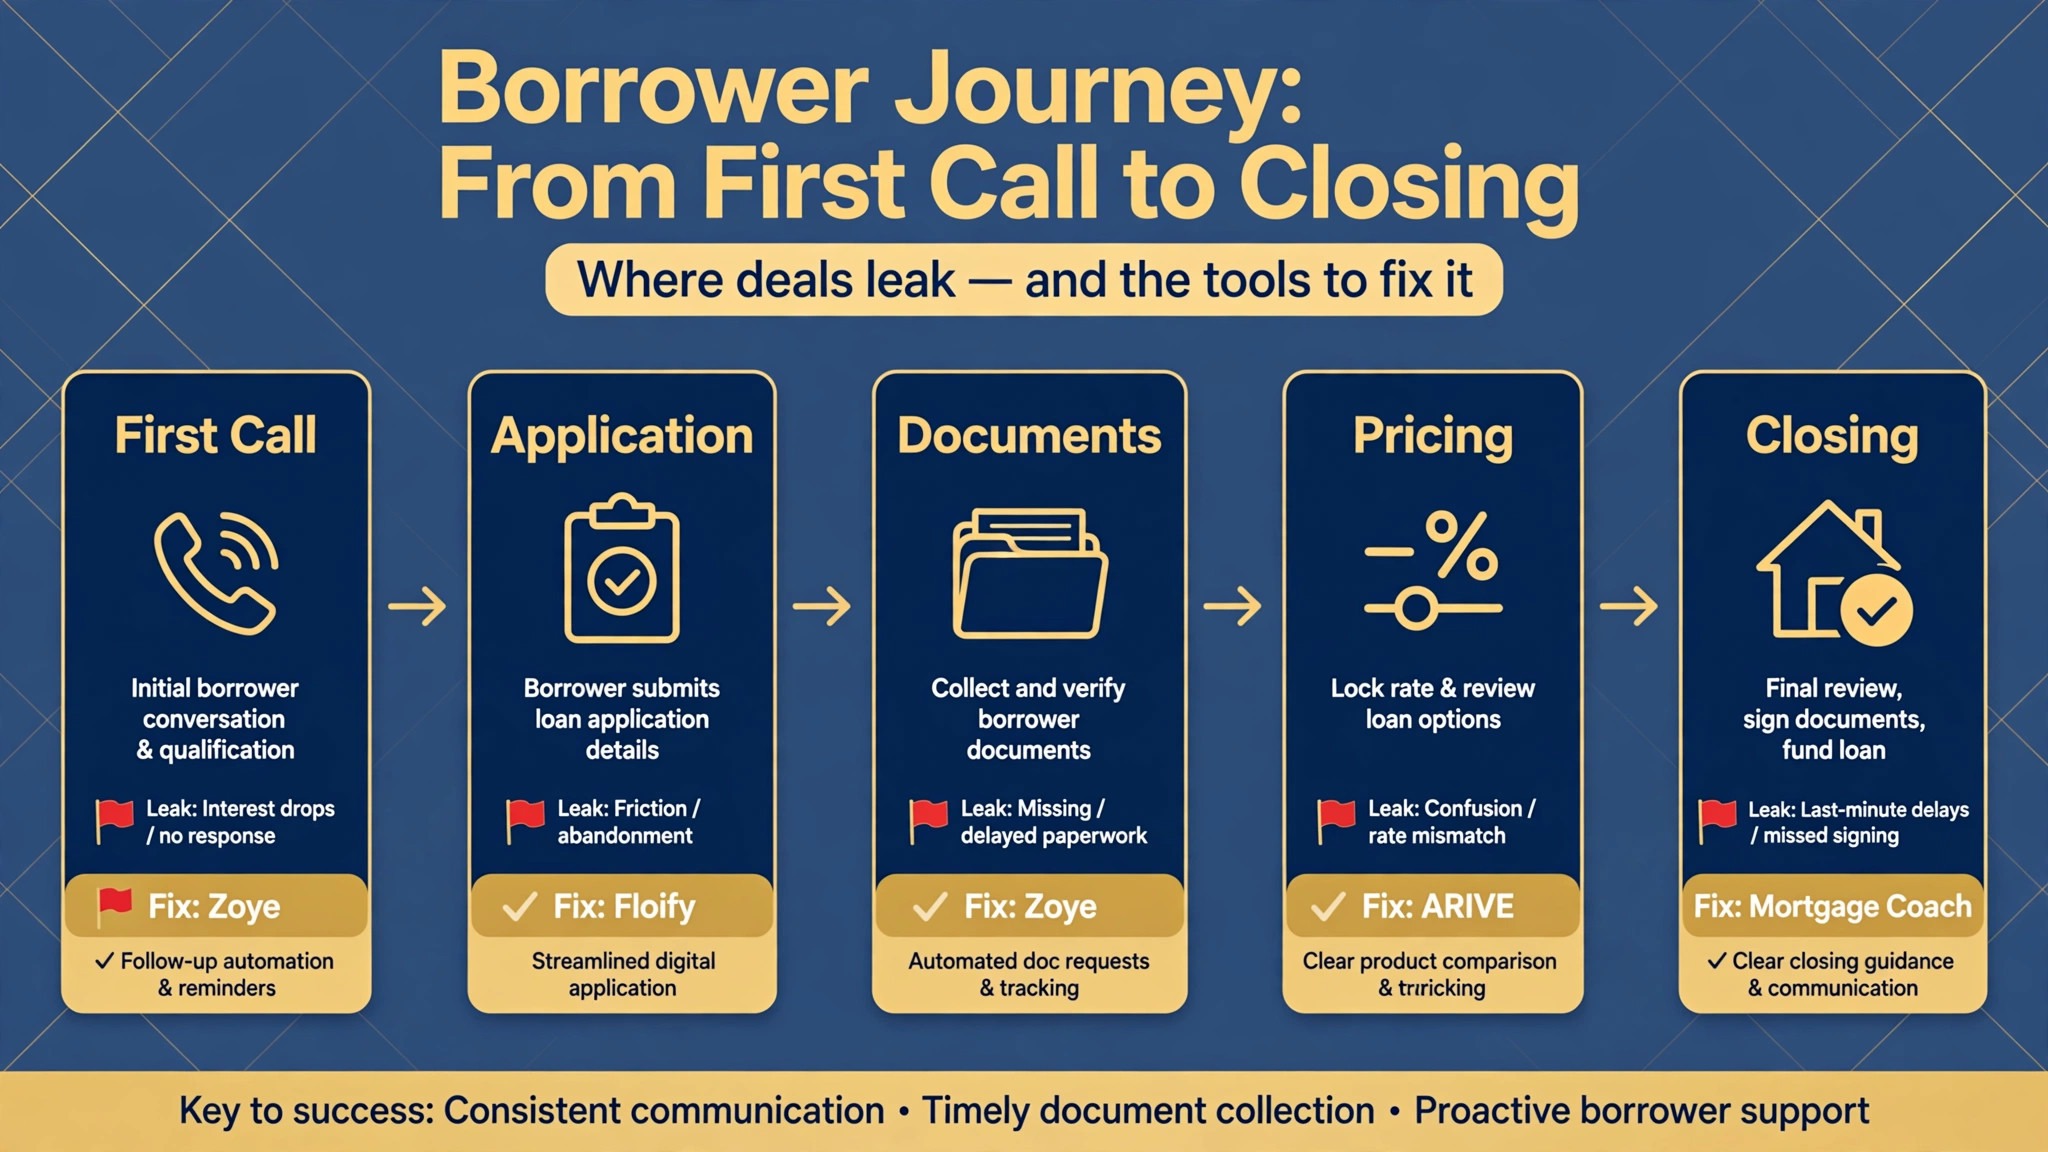
A mortgage broker loses most deals in the gaps, not in the pitch. The lead that waits two days for a callback, the document that sits unopened for a week, the past client who refinances with someone else because nobody called when rates moved. The best ai tools for mortgage brokers exist to close those gaps, because a follow up that goes out in minutes, a document that gets checked the day it arrives and a rate update that reaches the right borrower at the right time are the difference between a pipeline and a pile of names.
This guide compares eight tools on published prices, the job each one does best and the catch that only shows up after the contract is signed. Prices come from vendor pricing pages and third party roundups checked in November 2026, and where a vendor sells by quote only, this guide says so instead of guessing. The tools cover the whole broker workflow, from lead capture to the loan origination system, the pricing engine and the follow up that brings the next deal. The reviews below follow the loan from lead to close, so the best ai tools for mortgage brokers show up where the deal actually leaks.
One rule runs through the whole category, and it matters more than any feature. AI must never decide credit, price, lock or program steering, those stay with the licensed loan officer under the SAFE Act and state licensing. The tools below are bought to organize, draft and chase, not to decide, and any vendor that suggests otherwise should be treated with caution.
The Quick Shortlist
The table below matches each common broker job to the single tool that handles it best. Use it to narrow the best ai tools for mortgage brokers to two or three candidates before you read the full reviews. Prices are monthly list prices unless noted, and annual billing is usually cheaper than paying month to month.
| Job | Best tool | Why it wins |
|---|---|---|
| All in one AI workstation with guideline answers | Zeitro | Free account, with Strata guideline AI across 2,000 plus programs |
| Loan origination with a built in pricing engine | ARIVE | From 49 dollars and 99 cents per seat a month billed annually |
| All in one CRM, marketing and point of sale | BNTouch | Individual from 165 dollars a month, with 400 plus campaigns |
| Deepest reporting on Salesforce | Jungo | Lite at 96 dollars per user a month billed annually |
| Digital application plus document collection | Floify | From 49 dollars a month billed annually, with a free tier |
| Borrower presentations that explain the options | Mortgage Coach | Individual at 150 dollars per user a month |
| Live rates and market intelligence | MBS Highway | 199 dollars and 95 cents a month |
| Follow up, documents and partners for a small shop | Zoye | Starter at 29 dollars a month for up to 10 members |
The Five Tests Behind the Best AI Tools for Mortgage Brokers
A tool earned a place here only if it does a real broker job in 2026, not if it added an AI label to an old product. The best ai tools for mortgage brokers were tested on five things that decide whether a brokerage keeps paying after the trial.
First, the job it does, from lead follow up to document checks to rate updates, because a tool that does one job well beats a platform that does five jobs poorly. Second, whether the price is published or hidden behind a sales call, including setup fees and per user charges that change the real bill. Third, the loan origination connection, because a CRM that syncs with Encompass, LendingPad or Calyx saves the double entry that a standalone tool leaves behind.
Fourth, compliance behavior, because a tool that drafts a rate quote or a qualification verdict before a licensed officer signs off creates a licensing risk, not a time saving. Fifth, the catch, from quote only pricing that hides the cost until the demo to per loan fees that grow with volume.
The follow up test deserves a paragraph of its own, because it is where most brokerages leak. A CRM earns its keep when a past client gets a rate watch message at the right moment, a referral partner gets a thank you before the next deal, and a cold lead gets a callback inside the hour, not the week. The tools below differ on how much of that follow up they automate, and the right test is to run one real lead through the whole flow before you buy. If the lead reaches the officer with its documents attached and its history visible, the tool works.
| Check before you buy | What to ask | Why it matters |
|---|---|---|
| Price structure | Per user, per seat, or per loan | Per loan fees grow with volume |
| Loan system sync | Does it sync with your LOS, or export only | Sync saves double entry every file |
| Compliance guardrails | Does it draft quotes or verdicts on its own | Only a licensed officer decides credit and price |
| Lead follow up | How fast does a new lead reach the officer | Speed decides whether the lead converts |
| Setup and contract | Setup fee, and annual only or monthly | Setup fees add up across a team |
| Data consent | How does it handle call and text consent | Texting without consent creates legal risk |
The 8 Tools, Reviewed One by One
1. Zeitro
Starting price Free account, paid plans priced on request. Best for All in one AI workstation with guideline answers. Watch out Paid plans are quote only, so the full price needs a sales call.
Zeitro is the all in one AI mortgage workstation, covering lead capture, a digital point of sale, the pipeline and loan files, a pricing engine and Zeitro Strata guideline AI in one platform. The borrower application is simplified and backed by AI, with a one page application that takes a few answers and the borrower documents and builds the loan from them on a phone, so most borrowers finish in one sitting. When the file is ready, it goes to the loan origination system as FNM 3.4 or straight into Encompass.
The guideline AI is the feature that separates Zeitro from a plain workstation. Strata answers guideline questions with the guideline cited, from more than 2,000 programs and 100 plus investors, and it sorts programs into eligible and ineligible with the reasons given. A broker who used to search guideline PDFs for an hour can get a cited answer in minutes, and the citation is what makes the answer trustworthy enough to act on.
The catch is pricing. The free account for loan officers is real, and the paid plans are priced on request, so a brokerage cannot budget the full platform from the website. Zeitro still earns the top spot for brokers that want the whole workflow in one login, and buyers should ask for the paid figure early in the conversation.
2. ARIVE
Starting price From 49 dollars and 99 cents per seat a month billed annually. Best for Loan origination with a built in pricing engine. Watch out The AI features are in beta, so the AI side is still maturing.
ARIVE is the loan origination platform for independent mortgage brokers, and it earns its place because it builds the pricing engine into the origination system rather than bolting it on. Live pricing comes from integrated wholesale lenders, the application, the pipeline and the pricing live in one flow, and the broker stops switching between a pricing tool and a loan system for every file. The published price starts at 49 dollars and 99 cents per seat a month billed annually, which is the lowest published origination price on this list.
The strength is the single flow. A broker can take a borrower from application to pricing to file without exporting data between systems, and that continuity cuts the errors that come from retyping loan details. For a small brokerage that wants one system for origination and pricing, that single flow is the whole value, and the published price makes the decision easy to budget.
The catch is the AI maturity. ARIVE AI is in beta, and its document extraction was rolled back in August 2026, so a buyer who wants deep AI document handling today should look at the document tools further down this list. For origination plus pricing at a published price, ARIVE earns second place.
3. BNTouch
Starting price 165 dollars a month for Individual. Best for All in one CRM, marketing and point of sale. Watch out A five person team pays 570 dollars a month on Team, so the per user math matters.
BNTouch is the best all in one value for solo loan officers and small teams, because it publishes its price when most mortgage CRMs make you book a sales call. Individual costs 165 dollars a month with a one time 125 dollar activation fee, and Team costs 190 dollars a month plus 95 dollars per additional user. The Individual plan includes a digital 1003, a borrower portal, more than 400 prebuilt campaigns, a texting framework and the MAIA assistant, with native integrations to Encompass, Calyx and LendingPad.
The campaign library is the reason small teams adopt it. Four hundred plus prebuilt campaigns mean a solo officer can run rate watch, past client and referral partner follow up from day one without building a single workflow, and the MAIA assistant helps draft and organize the outreach. That ready made follow up is what a busy officer actually needs, since the alternative is a blank CRM that nobody has time to configure.
The catch is the team math. The Individual price is competitive for a solo officer, but at 190 dollars a month plus 95 dollars per additional user, a five person team pays 570 dollars a month, so a growing team should price the Team tier before it commits. BNTouch still earns its place as the strongest all in one value for small brokerages.
4. Jungo
Starting price 96 dollars per user a month billed annually for Lite. Best for Deepest reporting on Salesforce. Watch out Salesforce licensing sits on top, so the Jungo price is not the full bill.
Jungo is the CRM for loan teams already on Salesforce, because it adds the mortgage layer on top of the platform the team already runs. Jungo Lite costs 119 dollars per user a month billed monthly, or 96 dollars per user a month billed annually, and the Jungo Bundle costs 149 dollars billed monthly or 125 dollars billed annually, with a one time setup fee of 249 to 299 dollars depending on plan and billing. The Salesforce base gives it the deepest reporting on this list, with campaigns, partner tracking and pipeline views that a standalone CRM cannot match.
The advantage is the reporting depth. A sales manager can see the pipeline by officer, by partner and by stage, and the Salesforce integrations carry the loan data into the same views. For a team that already pays for Salesforce, that depth is worth more than a cheaper standalone CRM, because the team keeps one system of record instead of two.
The catch is the stack cost. The Jungo price does not include Salesforce licensing, so a team that is not already on Salesforce faces a second bill before Jungo does anything. For a Salesforce shop, Jungo earns its place as the deepest mortgage CRM here, and buyers should price the full stack before they sign.
5. Floify
Starting price From 49 dollars a month billed annually. Best for Digital application plus document collection. Watch out The AI features come through marketplace partners rather than built in, so confirm what is included.
Floify is the point of sale pick for brokers whose bottleneck is the borrower facing application. It gives borrowers a digital application form, collects documents, tracks conditions and keeps the file moving, with a free tier for fewer than ten applications a month and paid plans from 49 dollars a month billed annually, scaling to 500 to 2,000 dollars a month by application volume. For a brokerage that loses files to document chasing, that collection flow is the fix.
The strength is the borrower experience. A borrower who can apply, upload documents and see what is still needed from a phone finishes faster than one who emails PDFs back and forth, and the processor sees the same file status without asking. That shared visibility cuts the ten reminder calls that eat a processor week, and it shortens the loan cycle from the application side rather than the underwriting side.
The catch is the AI depth. Floify offers AI through marketplace partners rather than building it into the core product, so a buyer who wants document extraction and automated checks should confirm which partner is included and what it costs. As a digital point of sale with document collection, Floify earns its place, and it pairs well with a CRM rather than replacing one. A brokerage that already runs a CRM should trial Floify on a live file first, since the document flow is where the time saving shows up, and the trial will show whether the collection reminders actually cut the chasing.
6. Mortgage Coach
Starting price 150 dollars per user a month for Individual. Best for Borrower presentations that explain the options. Watch out Enterprise pricing for five plus users is custom, so a team price needs a quote.
Mortgage Coach, built by TrustEngine, is the borrower presentation product that has served the industry since 1997, and it earns its place because it turns a rate quote into a decision a borrower can understand. It builds interactive presentations that compare loan options, show the financial impact of each choice and explain the trade offs in plain language, so the borrower chooses with confidence rather than guessing. The Individual plan is published at 150 dollars per user a month, with live training and integrations to Encompass and the main pricing engines.
The value is the close. A borrower who understands why one option costs more now and less later is more likely to commit, and the presentation gives the loan officer a reason to call back with something useful rather than a status check. The integrations to Optimal Blue, Polly and Lender Price mean the numbers in the presentation match the pricing engine, so the officer is not retyping rates into a slide.
The catch is the team price. Enterprise pricing for five plus users is custom, so a brokerage should get the team figure in writing before it rolls the tool out to every officer. For a loan officer whose bottleneck is borrowers who cannot decide, Mortgage Coach is the best presentation tool on this list.
7. MBS Highway
Starting price 199 dollars and 95 cents a month. Best for Live rates and market intelligence. Watch out It is a market tool, not a CRM or a loan system, so it solves one job only.
MBS Highway is the market intelligence pick for brokers and lending teams that monitor rate activity closely. It gives access to live mortgage rates, investor guidelines and daily market trends, with interactive tools for comparing loan products, running affordability calculators and showing the financial impact of locking in a rate. The published price is 199 dollars and 95 cents a month on a flat monthly subscription, which makes it easy to budget.
The strength is timing. A broker who knows the market moved this morning can call the right borrower before the competition does, and the calculators turn that market move into a concrete payment comparison the borrower can act on. That speed is why MBS Highway shows up in so many broker stacks even though it does none of the origination work, because the rate conversation is the conversation that closes.
The catch is scope. MBS Highway does not manage leads, files or follow up, so a brokerage still needs a CRM and a loan system alongside it. For the rate and market job alone, it earns its place as the clearest window on the market, and it pairs with any CRM on this list.
8. Zoye
Starting price 29 dollars a month for Starter. Best for Follow up, documents and partners for a small shop. Watch out It is not a loan origination system, a borrower portal or a pricing engine, so it runs next to your LOS.
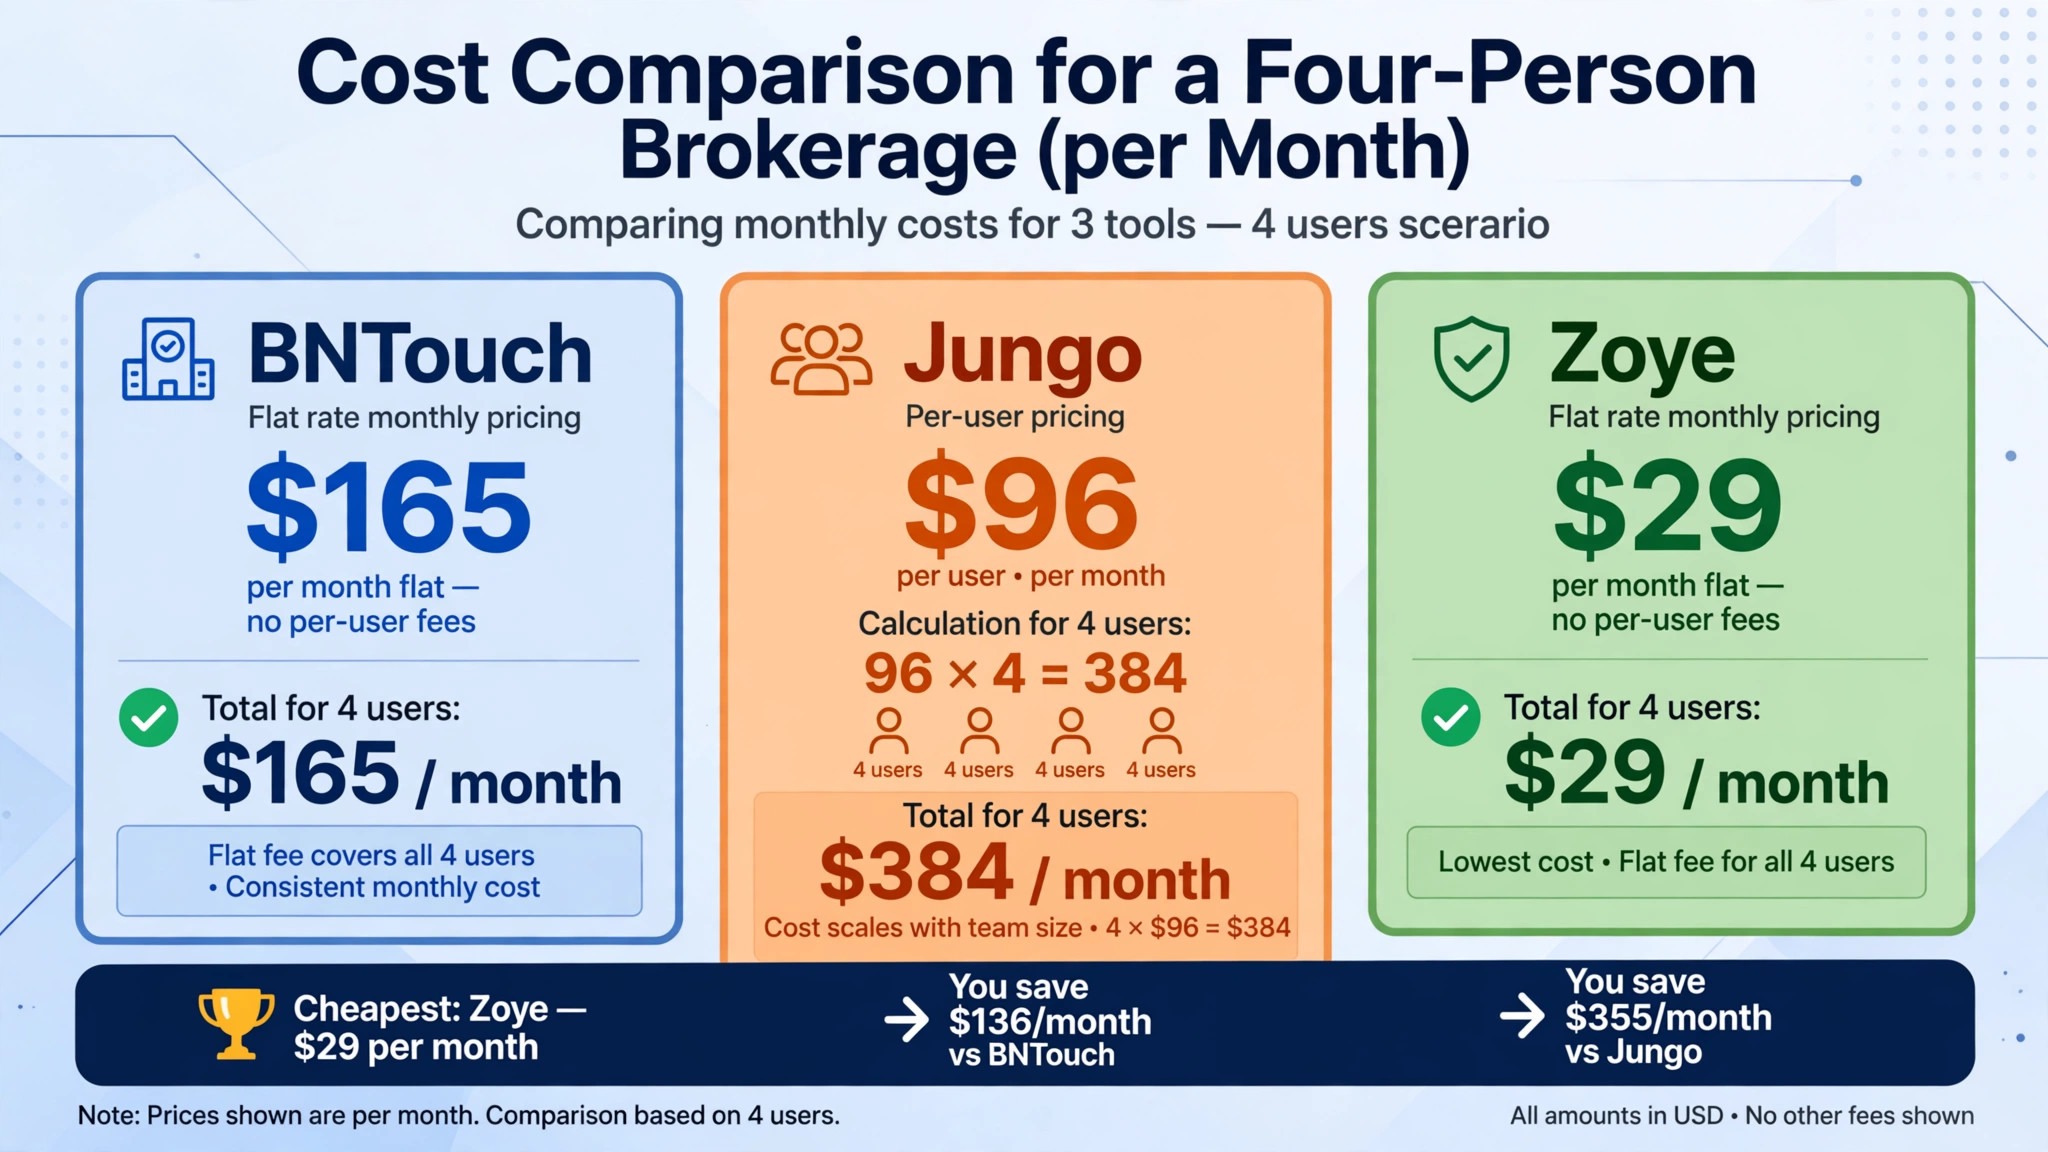
Zoye is the AI Business Operator for small brokerages, and it earns its place because it charges per workspace rather than per loan officer. Starter costs 29 dollars a month, or 23 dollars a month billed yearly, for up to ten members, Growth costs 59 dollars a month, or 47 dollars billed yearly, for up to twenty members, and Scale costs 119 dollars a month for up to one hundred members. A four person brokerage pays about 59 dollars a month on Growth, against about 380 dollars a month on BNTouch Team or 384 dollars on Jungo at list prices.
The strength is the connected workspace. The CRM, deals, tasks, calendar, documents, email tracking, reports, workflow automations and WhatsApp automations sit in one place, with an AI that operates them for the team, and partners are tracked as linked records with a report per partner. For a small brokerage whose deals leak through follow up, that connected follow up is the whole value, and the workspace price makes it affordable for a team that cannot justify a per user CRM.
The catch is the boundary. Zoye takes no 1003 application, pulls no credit, does not watch market rates and makes no claim to meet a lending compliance standard, so it runs next to the loan system rather than replacing it. For a small shop that needs follow up fixed at a workspace price, Zoye closes the list as the cheapest credible option.
Side by Side Comparison
The table below puts the best ai tools for mortgage brokers side by side on price, best job and free option, so a brokerage can compare the published prices against the quote only tools before shortlisting.
| Tool | Starting price | Best for | Free option |
|---|---|---|---|
| Zeitro | Free account, paid plans on request | All in one AI workstation with guideline answers | Yes |
| ARIVE | From 49 dollars and 99 cents per seat a month, annual | Loan origination with a built in pricing engine | No |
| BNTouch | 165 dollars a month | All in one CRM, marketing and point of sale | No |
| Jungo | 96 dollars per user a month, annual | Deepest reporting on Salesforce | No |
| Floify | From 49 dollars a month, annual | Digital application plus document collection | Yes, under 10 applications a month |
| Mortgage Coach | 150 dollars per user a month | Borrower presentations that explain the options | No |
| MBS Highway | 199 dollars and 95 cents a month | Live rates and market intelligence | No |
| Zoye | 29 dollars a month | Follow up, documents and partners for a small shop | Almost Free plan at 5 dollars a month |
How to Pick the Right Tool for Your Brokerage
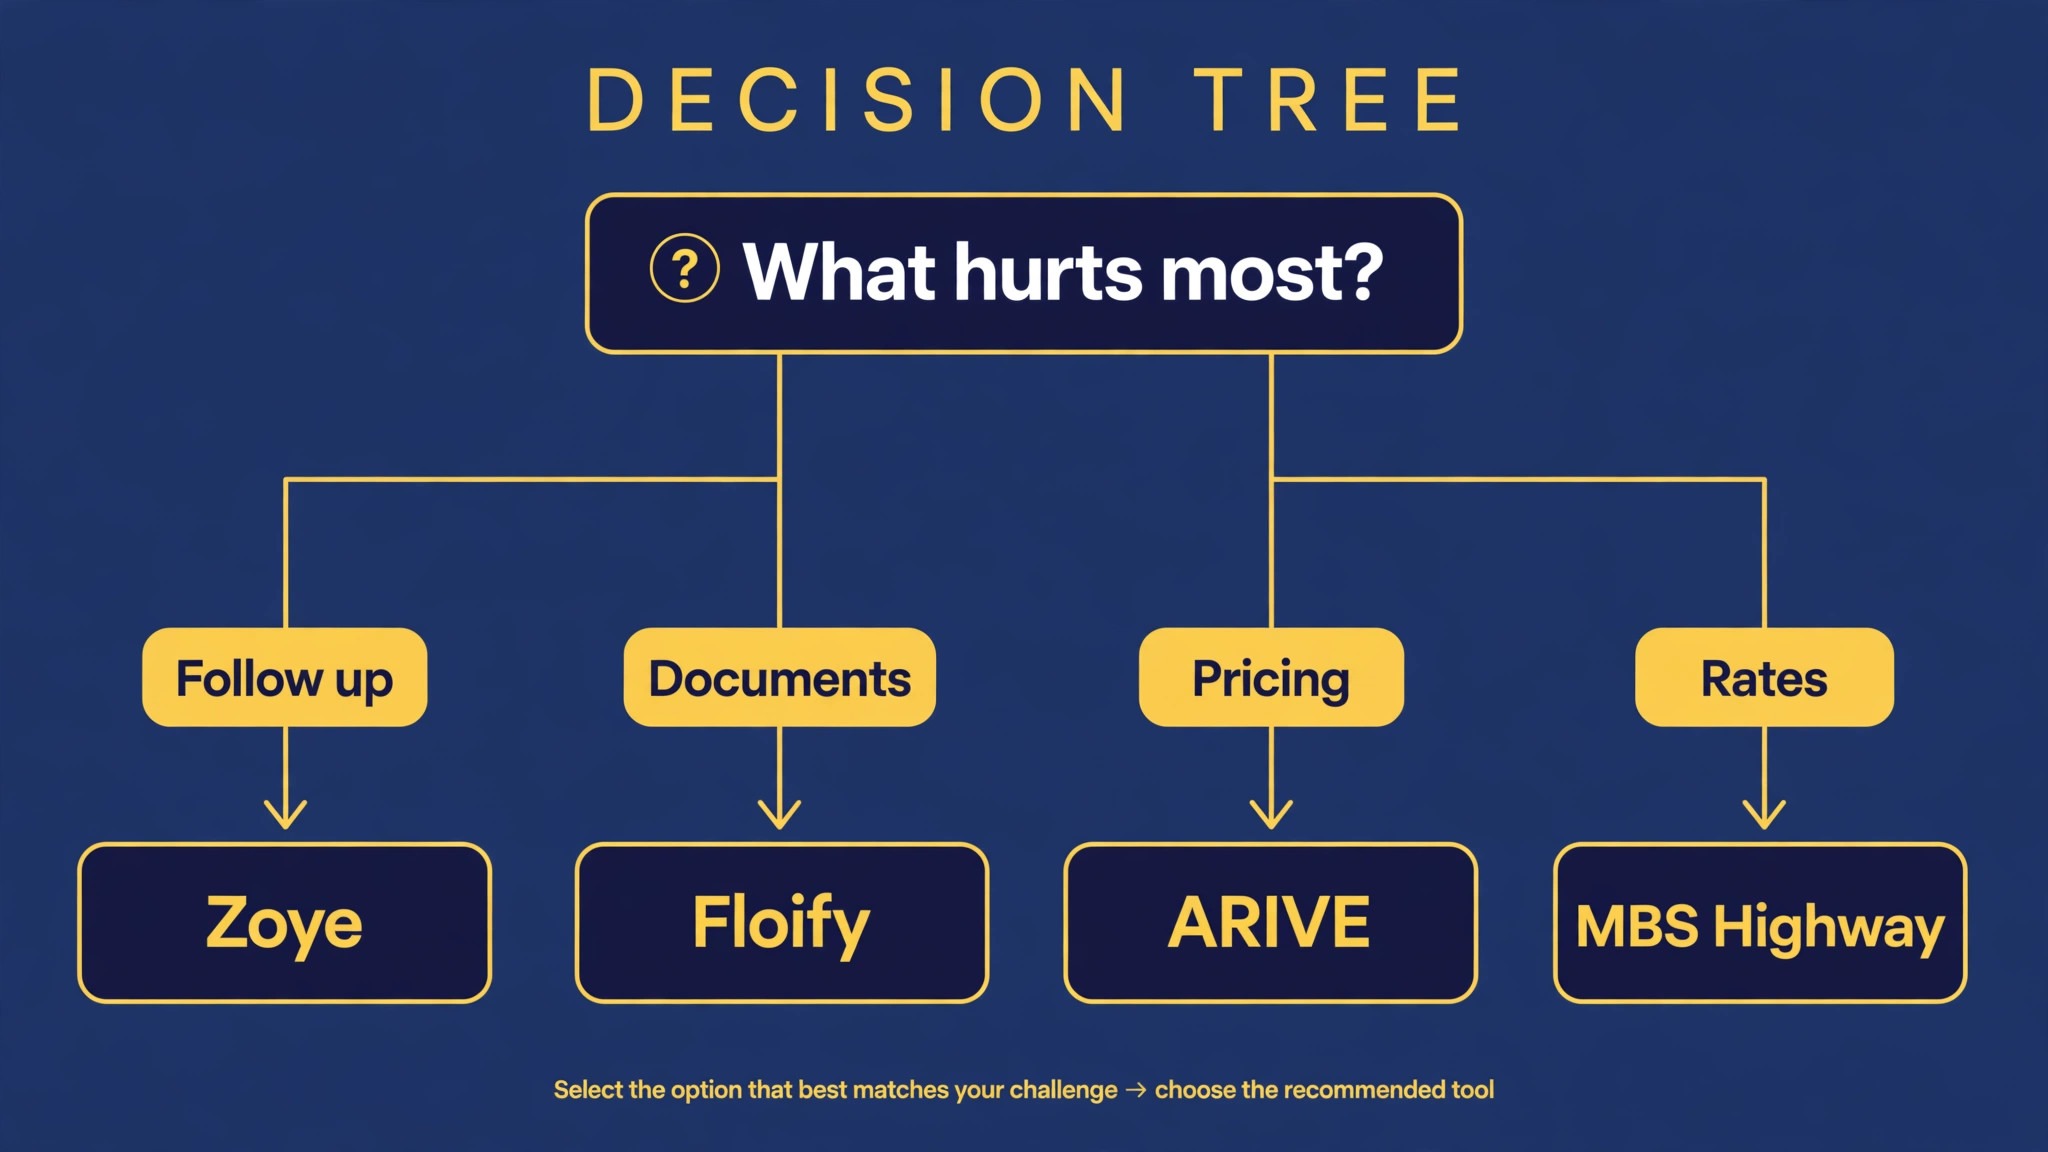
The best ai tools for mortgage brokers are not the ones with the longest feature list. They are the ones that fix the gap your brokerage feels every week. A brokerage that loses leads to slow follow up should buy Zoye or BNTouch. A brokerage that loses files to document chasing should buy Floify or Zeitro. A brokerage that cannot explain options to borrowers should buy Mortgage Coach. A brokerage that misses rate moves should buy MBS Highway. A team already on Salesforce should buy Jungo. Start from the gap, not from the vendor homepage.
Budget the full stack, not the headline seat price. The table below shows what a four person brokerage actually pays in year one for the most common combinations, using starting annual prices. Per user pricing multiplies fast, and setup fees add a one time line, so ask for both in writing before you sign.
| Stack for a four person brokerage | Monthly cost, annual billing | What it covers |
|---|---|---|
| Zoye Growth | 47 dollars | Follow up, documents and partners for 20 members |
| BNTouch Team, 4 users | 380 dollars | CRM, marketing and point of sale |
| Jungo Lite, 4 users | 384 dollars | Mortgage CRM on Salesforce, before Salesforce licensing |
| ARIVE, 4 seats | About 200 dollars | Origination plus built in pricing engine |
| Floify plus Mortgage Coach | About 199 dollars | Application plus borrower presentations for one officer |
Frequently Asked Questions
What is the cheapest good AI tool for a mortgage broker
Zoye Starter at 29 dollars a month for up to ten members is the cheapest paid entry, and Growth at 59 dollars a month covers twenty members with automations. Floify from 49 dollars a month billed annually is the cheapest point of sale, and ARIVE from 49 dollars and 99 cents per seat a month is the cheapest origination system with a built in pricing engine. The cheapest stack that actually works for a small brokerage is usually Zoye for follow up plus Floify for applications, which costs less than 110 dollars a month for a four person team.
Do AI tools decide whether a borrower qualifies
No, and any tool that suggests it can should be treated with caution. AI must never deliver a rate quote, a lock decision, a program steering recommendation or a qualification verdict, because those stay with the licensed loan officer under the SAFE Act and state licensing. Use AI for intake, document checks, drafting and follow up, and keep every credit, pricing and lock decision with the officer who holds the license. A tool that respects that line is a safe buy, and one that crosses it is a risk.
Which tool is best for lead follow up
BNTouch is the best single tool for most brokerages, because its 400 plus prebuilt campaigns cover rate watch, past client and referral partner follow up from day one, with a published price. Zoye is better when the budget is tight and the team wants a workspace price rather than a per user price. Jungo is better when the team already runs Salesforce and wants the deepest reporting on follow up. Pick BNTouch if you want ready made campaigns, Zoye if you want the lowest price, and Jungo if you want Salesforce depth.
How much should a four person brokerage budget for AI tools
A realistic year one budget for the best ai tools for mortgage brokers is 47 to 380 dollars a month for a CRM or follow up tool, and 200 to 500 dollars a month once you add an origination system or a point of sale. Per user pricing is the line that surprises buyers, so multiply the headline by your officer count before you compare. Quote only tools need a sales call to price, so budget a range and get the setup fee and the per user figure in writing.
Our Verdict
If you buy one tool this quarter, buy BNTouch Individual if you work solo, or Zoye Growth if you run a small team. BNTouch covers the most of the broker job at a published price a solo officer can afford, with campaigns that start working on day one, while Zoye covers the same follow up job for a whole team at a workspace price that undercuts every per user rival. The best ai tools for mortgage brokers earn their keep by closing the gaps where deals leak, and both picks do that from the first week, without an enterprise contract.
Whatever you pick, start with the gap, trial with a real lead, and keep every credit, pricing and lock decision with the licensed officer. The tools on this list all work. The difference is whether the tool matches the job your brokerage actually needs done, and whether you measure the return in loans closed rather than in features used.